How to Build a 13-Week Cash Flow Forecast for a Small Business
You can be profitable on paper and still not have enough money in the bank to make payroll on Friday. That’s not a hypothetical—it’s common for otherwise healthy small businesses to run into financial pressure, even when sales look strong. A profit-and-loss statement tells you whether the business made money over a month or a quarter. It doesn’t tell you whether you’ll have cash in the account on a specific Tuesday to cover a supplier invoice. A monthly forecast can hide a tight week too, burying it inside an otherwise comfortable-looking month.
That’s the gap this kind of planning is built to close. Instead of looking at your finances one month at a time, a 13-week cash flow forecast breaks the next three months into individual weeks, so you can see precisely when money is coming in, when it’s going out, and where the tight spots are—before they become emergencies.
This guide walks through what the forecast actually is, why 13 weeks is the sweet spot, and exactly how to build one—step by step, with a worked numerical example, ready-to-copy spreadsheet formulas, and a weekly review checklist you can start using today.
What Is a 13-Week Cash Flow Forecast?
It’s a rolling, week-by-week projection of the cash you expect to receive and the cash you expect to pay out over the next thirteen weeks. Each column in the spreadsheet represents one week. Instead of tracking accounting profit, it tracks actual cash movement—real money hitting or leaving your bank account.
Unlike a static annual budget, this forecast is meant to move. Every week, you drop the week that just ended, update your numbers with what actually happened, and add a new thirteenth week to the far end. It keeps rolling forward, always giving you a fresh three-month runway.
Formula box
Net Cash Flow = Total Cash Inflows − Total Cash Outflows
Ending Cash Balance = Beginning Cash Balance + Net Cash Flow
One detail that trips people up early on: this week’s ending cash balance becomes next week’s beginning cash balance. The whole spreadsheet is a chain—get one week wrong, and it throws off everything after it.
Why Does a Cash Flow Forecast Cover 13 Weeks?
Thirteen weeks isn’t a random number—it maps almost exactly to a business quarter, which makes it long enough to be genuinely useful for planning and short enough to stay accurate.
A few reasons this window works so well for small businesses specifically:
- Weekly detail surfaces short-term risk that a monthly view smooths over.
- Thirteen weeks is still a long enough horizon to actually make decisions—cut a cost, chase an invoice, or line up financing—before a shortfall hits.
- Irregular obligations like payroll, rent, quarterly taxes, loan payments, and vendor bills all land on different schedules. A weekly view is one of the few formats that shows all of them on the same timeline at once.
- It gives you enough lead time to arrange funding or adjust spending, rather than reacting the week cash actually runs short.
Who Should Use a 13-Week Cash Flow Forecast?
This isn’t only a tool for businesses already in trouble. A few situations where it earns its keep:
- Service businesses with customers who pay on their own schedule, not yours
- Retailers with seasonal swings in sales
- Product businesses that have to buy inventory before they sell it
- Fast-growing businesses where expenses are scaling ahead of collections
- Businesses currently facing—or trying to avoid—a cash shortage
- Businesses preparing to approach a lender or investor
- Agencies and contractors with lumpy, project-based revenue
Even a stable, comfortably profitable business benefits from this kind of liquidity planning—it’s less about crisis response and more about staying ahead of the calendar.
If you are preparing for growth, use this forecast alongside our guide on how to scale a small business without burning cash.
13-Week Forecast vs. Budget vs. Profit-and-Loss Statement
These three tools get confused constantly, but they answer different questions.| Financial Tool | Primary Purpose | Time Focus | Tracks |
|---|---|---|---|
| 13-week cash flow forecast | Short-term liquidity | Weekly | Actual cash timing |
| Business budget | Spending and revenue plan | Monthly / annual | Planned performance |
| Profit-and-loss statement | Profitability measurement | Historical periods | Revenue and expenses |
The distinction that matters most: profit and cash are not the same thing. You can invoice $50,000 this month and record it as revenue, but if the customer doesn’t pay for 45 days, that profit does nothing for your bank balance next week. Of the three tools above, only the weekly forecast cares about when money actually moves.
Information You Need Before You Start
Gather this before you open a spreadsheet—trying to build the forecast while hunting for numbers is how errors creep in.
- Current bank account balances
- Outstanding customer invoices
- Expected collection dates for each one
- Confirmed orders and contracts
- Payroll schedule
- Rent and utility payment dates
- Supplier invoices and terms
- Inventory purchase plans
- Loan and credit card payment schedules
- Tax payment dates
- Software subscription renewals
- Any planned one-time purchases
- Owner contributions or withdrawals
Important note: Place an invoice in the week you realistically expect to collect the cash, not the week you issue it. This one habit is responsible for more forecast errors than anything else on this list.
How to Build a 13-Week Cash Flow Forecast in 7 Steps
Step 1—Create the 13-Week Spreadsheet
Set up your columns first:| Cash-Flow Category | Week 1 | Week 2 | Week 3 | … | Week 13 |
|---|---|---|---|---|---|
Organize your rows into four groups:
- Beginning cash balance
- Cash inflows
- Cash outflows
- Net cash flow and ending balance
Label each week with its actual start and end date—not just “Week 1, Week 2.” “You’ll thank yourself later when you’re checking the sheet against your bank statement.
Step 2—Enter the Beginning Cash Balance
Include:
- Your operating bank account balance
- Available business savings
- Any cash immediately accessible to the business
Exclude:
- Unused credit line
- Unpaid invoices (they’re not cash yet)
- Inventory value
- Restricted or reserved funds
- Personal bank balances
Pull the starting number straight from your most recent bank statement or online balance—don’t estimate it.
Step 3 — Forecast Weekly Cash Inflows
Common inflow categories to map out week by week:
- Customer invoice collections
- Cash and card sales
- Subscription payments
- Customer deposits
- Advance payments
- Loan proceeds
- Owner capital contributions
- Tax refunds
- Asset-sale proceeds
- Other confirmed receipts
Place each expected payment in the week you realistically expect to receive it, not the week the sale happens or the invoice goes out.
Use three confidence levels:
- Confirmed—the payment date is essentially locked in
- Probable—payment is expected but not guaranteed
- Uncertain—the sale or collection isn’t confirmed yet
Keep uncertain revenue out of your base numbers, or isolate it in a separate scenario. Mixing hopeful figures into your base case is one of the fastest ways to make the whole exercise unreliable.
Step 4 — Forecast Weekly Cash Outflows
Payroll and people costs
- Employee wages
- Payroll taxes
- Contractor payments
- Benefits
Operating expenses
- Rent
- Utilities
- Insurance
- Software
- Marketing
- Shipping
- Professional services
Suppliers and inventory
- Vendor invoices
- Raw materials
- Inventory orders
- Freight and delivery costs
Financing and taxes
- Loan repayments
- Credit card payments
- Interest
- Sales tax
- Payroll tax
- Estimated income tax
One-time payments
- Equipment purchases
- Repairs
- Annual renewals
- Legal expenses
- Owner distributions
Just like inflows, place each payment in the week you actually expect to pay it—not the invoice due date, if those differ.
Step 5—Calculate Net Cash Flow and Ending Cash
For every single week:
Total Cash Available = Beginning Cash Balance + Total Cash Inflows
Net Cash Flow = Total Cash Inflows − Total Cash Outflows
Ending Cash Balance = Beginning Cash Balance + Net Cash Flow
Week 1’s ending balance should feed directly into Week 2’s beginning balance, and so on down the line. Set it up right once, and the whole sheet recalculates itself as numbers change upstream.
Step 6 — Set a Minimum Cash Balance
Don’t wait until the balance actually goes negative to react—set a floor in advance. Base it on whichever of these fits your business:
- One full payroll cycle
- One month of essential expenses
- A minimum required by a loan covenant
- An emergency operating reserve
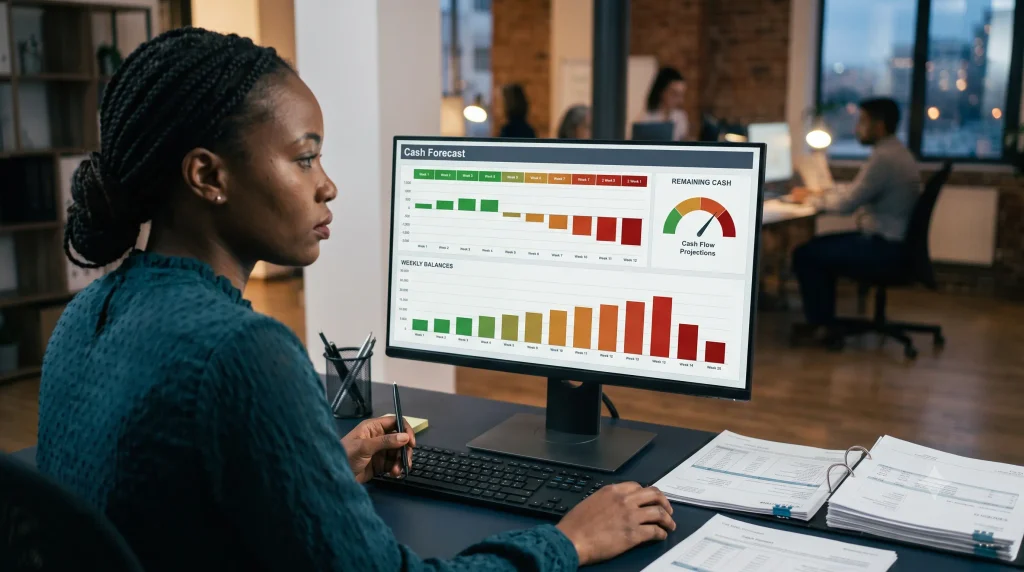
Use conditional formatting to make risk visible at a glance:
- Green—comfortably above the minimum
- Yellow—approaching the minimum
- Red—below the minimum
- Dark red—negative cash balance
Step 7 — Review and Roll the Forecast Every Week
This is the step most businesses skip—and it’s the one that actually makes the exercise valuable. A forecast built once and left alone stops reflecting reality within a few weeks.
Each week:
- Compare last week’s forecast to what actually happened.
- Update any customer payments that came in late.
- Add new invoices and expenses as they appear.
- Revise assumptions that turned out to be off.
- Move the completed week into an “actuals” column, or remove it.
- Add a fresh Week 13 to the end of the sheet.
- Assign a specific action and owner to any shortfall you spot.
The U.S. Small Business Administration’s financial forecasting guidance similarly recommends reviewing actual results against projections and adjusting business decisions accordingly.
13-Week Cash Flow Forecast Example for a Small Business
To make this concrete, here’s a hypothetical example based on a typical small service business. The numbers are illustrative—built to show how the mechanics work and how a shortfall gets caught early—not pulled from an actual company’s books.
Assumptions
- Beginning cash balance: $25,000
- Weekly customer collections: $8,000–$14,000
- Biweekly payroll: $9,000
- Monthly rent: $3,000
- Week 6 tax payment: $8,500
- Week 7 insurance renewal: $4,000
- Minimum desired cash balance: $10,000
| Cash-Flow Item | Week 1 | Week 2 | Week 3 | Week 4 | Week 5 | Week 6 | Week 7 |
|---|---|---|---|---|---|---|---|
| Beginning cash | $25,000 | $27,000 | $23,500 | $27,500 | $24,500 | $23,500 | $12,500 |
| Customer collections | $12,000 | $8,500 | $14,000 | $10,000 | $8,000 | $9,500 | $8,500 |
| Total inflows | $12,000 | $8,500 | $14,000 | $10,000 | $8,000 | $9,500 | $8,500 |
| Payroll | $0 | $9,000 | $0 | $9,000 | $0 | $9,000 | $0 |
| Rent | $3,000 | $0 | $0 | $3,000 | $0 | $0 | $3,000 |
| Tax payment | $0 | $0 | $0 | $0 | $0 | $8,500 | $0 |
| Insurance renewal | $0 | $0 | $0 | $0 | $0 | $0 | $4,000 |
| Other payments | $7,000 | $3,000 | $10,000 | $1,000 | $9,000 | $3,000 | $3,500 |
| Total outflows | $10,000 | $12,000 | $10,000 | $13,000 | $9,000 | $20,500 | $10,500 |
| Ending cash | $27,000 | $23,500 | $27,500 | $24,500 | $23,500 | $12,500 | $10,500 |
Note: figures are simplified for illustration and rounded for readability.
The first five weeks look comfortable—ending cash stays well above the $10,000 minimum. But Week 6 is where the pressure builds: the $8,500 tax payment lands alongside the $9,000 payroll and normal operating costs, pulling the ending balance down to $12,500. Week 7 adds the $4,000 insurance renewal, and the ending balance drops to $10,500—just above the floor, with almost no cushion left.
This is exactly the kind of pressure point a monthly view would likely miss, since it’s buried inside an otherwise healthy quarter. Spotting it in Week 1 instead of Week 6 changes what a business owner can actually do about it—delay a non-essential purchase, follow up on a slow-paying invoice, or set aside part of the stronger Week 3 collections in advance. Without a week-by-week view, the same business might only notice the squeeze once the tax bill is already due.
How to Set Up 13-Week Cash Flow Forecast Formulas
You don’t need anything fancy—Excel or Google Sheets handles this easily. Here are the core formulas to drop in (adjust row numbers to match your own layout):
- Total inflows:
=SUM(B5:B10) - Total outflows:
=SUM(B14:B25) - Net cash flow:
=B11-B26 - Ending cash balance:
=B3+B27
If you are unfamiliar with spreadsheet ranges, Microsoft provides a straightforward explanation of the Excel SUM function.
For Week 2’s beginning-balance cell, reference Week 1’s ending balance directly—for example, =B28 if B28 contains Week 1’s ending cash. Repeat that same reference pattern going into each following week.
Once these are set up in Week 1’s column, copy them across all 13 weeks, and the sheet recalculates automatically as you update your numbers.
How to Handle Late Payments in a 13-Week Cash Flow Forecast
Customer payments are almost always the least predictable input in this kind of planning—here’s how to tighten that up.
Use historical payment behavior.
Look at how long your customers typically take to pay after you invoice them, not how fast your payment terms say they should.
Review individual invoices.
Don’t apply your average collection rate blindly to every large invoice—a single big customer paying late can throw off the whole week.
Separate confirmed and uncertain receipts
Never let an unconfirmed sale sit in your base numbers dressed up as guaranteed cash.
Update payment dates weekly
The moment a payment goes late, move it to the next realistic week—don’t leave it sitting in the past pretending it already happened.
Build Three Cash Flow Scenarios
A single-scenario forecast tells you what you hope happens. Building out best, base, and worst cases tells you what could actually happen—and that’s where the real planning value comes from.
Base-case forecast
Your most realistic estimate of collections and expenses, grounded in actual customer behavior and confirmed obligations.
Best-case forecast
Faster collections, stronger sales, and fewer unexpected expenses than your base case assumes.
Worst-case forecast
Delayed payments, softer sales, or unplanned costs stacking up at once.
| Assumption | Best Case | Base Case | Worst Case |
|---|---|---|---|
| Customer collections | Early | Expected timing | Delayed |
| Sales | Above plan | Realistic | Below plan |
| Unexpected costs | Low | Moderate | High |
| Cash position | Strong | Manageable | Possible shortfall |
Running all three side by side gives you an early warning system. If your worst-case scenario shows a shortfall in Week 8, you have several weeks to act on it—not a couple of days.
What to Do When the Forecast Shows a Shortfall
Spotting a shortfall is only useful if you follow it with action. Here’s where to start.
Accelerate cash inflows.
- Follow up on overdue invoices
- Ask for customer deposits upfront
- Bill faster and more often if needed
- Consider an early-payment discount
- Sell unused business assets
If limited cash is restricting growth, these strategies can help you scale sales without upfront costs.
Reduce or delay outflows
- Postpone nonessential expenses
- Adjust the timing of inventory orders
- Reduce owner withdrawals temporarily
- Convert annual payments into installments where possible
For additional ways to protect your cash position, see our guide to scaling a small business without increasing operating costs.
Negotiate payment timing.
- Ask suppliers to extend payment terms
- Restructure an existing payment schedule
- Split large bills into smaller installments
Arrange funding early.
- Business line of credit
- Working-capital loan
- Invoice financing
- Owner capital injection
Each of these financing options comes with its own trade-offs in cost and flexibility—none is a one-size-fits-all fix. The right choice depends on your credit position, how quickly you need the cash, and what you can realistically repay.
Common 13-Week Cash Flow Forecast Mistakes
Treating sales as immediate cash
A closed sale isn’t cash until it’s collected. Record it in the week you expect payment, not the week you make the sale.
Assuming every invoice will be paid on time
Build in a realistic buffer based on actual customer payment history, not your invoice terms.
Forgetting tax and annual payments
These large, infrequent payments are a common cause of unexpected shortfalls—map them onto the calendar early.
Using overly optimistic projections
A forecast built on overly optimistic assumptions can create false confidence and delay corrective action. Base projections on realistic collection dates and known obligations.
Including unused credit as cash
Available credit is a backup, not a cash balance. Keep it out of your base numbers.
Mixing personal and business finances
Keep the two completely separate, or the forecast will lose accuracy fast.
Ignoring small recurring expenses
Subscriptions and small recurring fees add up and can quietly erode your cash position.
Failing to compare forecast with actual results
Without this comparison, you won’t know whether your assumptions are actually reliable.
Creating the forecast once and never updating it
A forecast that isn’t updated weekly stops functioning as a forecast—it becomes a one-time guess with a spreadsheet attached.
Weekly Review Checklist
Run through this every week to keep the numbers accurate and useful:
- Does the starting balance match the bank?
- Which receipts arrived late?
- Which expenses came in higher than expected?
- Are payroll and taxes fully covered?
- When does cash fall below the minimum threshold?
- Which assumption is currently least reliable?
- Can any upcoming payment be safely delayed?
- Which customer invoices need a follow-up call?
- Is external funding worth arranging now?
- Who is responsible for each corrective action?
Frequently Asked Questions
Why is a cash flow forecast 13 weeks?
Thirteen weeks maps closely to a business quarter, giving enough detail to catch short-term risk while staying long enough to actually act on it. It’s the standard window for this kind of planning because it balances accuracy with usable lead time.
How often should the forecast be updated?
Weekly. Update actual results, adjust assumptions, and roll the forecast forward by adding a new week at the end. A forecast that isn’t updated regularly loses accuracy quickly.
Should unpaid invoices be included?
Yes, but only in the week you realistically expect to collect payment—not the week the invoice was issued. Separate confirmed collections from uncertain ones.
Can this be built in Excel?
Yes. Excel or Google Sheets both work well. You only need basic SUM and subtraction formulas to link beginning balances, inflows, outflows, and ending balances across 13 columns.
What is the difference between cash flow and profit?
Profit measures revenue minus expenses over a period, regardless of when money actually moves. Cash flow tracks the real timing of money entering and leaving your bank account, which is what determines whether bills get paid.
What is the difference between a 13-week and a 12-month forecast?
A 13-week forecast tracks weekly detail over roughly a quarter, useful for short-term liquidity decisions. A 12-month forecast covers a full year at a broader, usually monthly, level—better for annual planning than for catching a near-term cash crunch.
How accurate should the forecast be?
Near-term weeks (1–4) should be quite accurate, since they’re based on confirmed invoices and known bills. Weeks further out will naturally be less precise—that’s normal, and it’s why weekly updates matter so much.
What should I do if the forecast shows negative cash?
Act early: accelerate collections, delay non-essential outflows, negotiate payment terms with suppliers, and explore funding options before the shortfall actually arrives.
Final Thoughts
Building a 13-week cash flow forecast isn’t about predicting the future perfectly—it’s about seeing pressure points early enough to actually do something about them. Start with your real, verified bank balance. Be honest about when customers actually pay, not when you’d like them to. Build in payroll, taxes, and the large irregular bills that tend to catch businesses off guard. And treat the forecast as a living document—update it weekly, compare it against what actually happened, and roll it forward.
Start this week: pull up your current bank balance, list the cash you realistically expect to collect and pay out over the next seven days, and build out Week 1. Update it every seven days from there, and cash-timing surprises become far easier to catch before they turn into a real problem.