How to Create a Small Business Budget That Actually Works
A small business budget should do more than show you where your money went last month. It should tell you how much you can safely spend, save, reinvest, and keep in reserve for the months that don’t go as planned. Most budgets fail not because the owner didn’t try, but because the numbers were built on hope instead of history.
This guide walks through a small business budget that actually works—built from real revenue, real expenses, and a review process you’ll actually stick to.
Quick Answer: How Do You Create a Small Business Budget?
A working small business budget comes down to seven steps: Review your last 6–12 months of financial data, estimate revenue conservatively, separate fixed and variable expenses, account for taxes and irregular costs, calculate your expected gross profit, operating costs, and cash flow, set spending priorities, then compare actual results to your budget every month and adjust. None of these steps are complicated on their own—the failure usually happens when one gets skipped.
What Is a Small Business Budget?
A small business budget is a written plan for what you expect to earn and spend over a set period, usually a month or a year. It covers expected revenue, expected expenses, expected profit, available cash, savings or reserves, and where you’ll direct spending first. Think of it as a decision-making tool, not just a record-keeping exercise.
Budget vs. Forecast: What’s the Difference?
A budget is what you plan to earn and spend. A forecast is your updated expectation based on new information as the month or year unfolds. You typically set a budget for a defined period, then update your forecast as actual results and new information come in—the two work together, not against each other. For a deeper look at how planning and monitoring fit together, Australia’s official small business budgeting guide walks through both in practical terms.
Why Most Small Business Budgets Don’t Actually Work
Plenty of business owners build a budget once, feel good about it, and then watch it fall apart within a few months. Here’s what usually goes wrong.
Revenue gets overestimated based on a strong month instead of an average one. Small recurring expenses like subscriptions and processing fees get left out entirely. Fixed and variable costs get lumped together, making it impossible to see your true break-even point. Taxes and irregular annual bills are ignored until they hit. And perhaps most commonly, the budget is created once and never touched again.
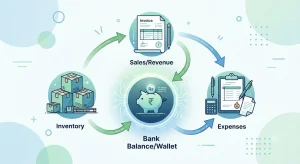
One distinction matters more than almost anything else: profit is not the same as cash in the bank. A business can be profitable on paper and still run short on cash if the timing of payments doesn’t line up—which is exactly why cash flow management deserves its own section further down.
Step 1: Start With Your Last 6–12 Months of Financial Data
Before projecting anything forward, pull together what actually happened. Gather your bank statements, sales records, invoices, accounting reports, credit card statements, payroll records, subscriptions, tax payments, and loan payments. This is your baseline—everything else in the budget builds on it.
If your business is less than 12 months old, use whatever sales data you do have, combined with realistic assumptions, industry benchmarks, supplier quotes, and expected customer volume. Established businesses lean on history; new businesses lean on informed estimates.
Step 2: Estimate Your Monthly Revenue Conservatively
Don’t build your budget around your best month ever. Use a simple formula instead: Expected Monthly Revenue = Expected Customers × Average Sale. For example, 80 customers at a $75 average sale gives you a projected $6,000 in monthly revenue.
From there, build three scenarios — conservative, expected, and optimistic — and base your core spending plan on the conservative number. That way, an average month still keeps your business on solid ground.
Step 3: List Every Business Expense
Now separate your costs into two clear categories. Fixed expenses stay roughly the same every month regardless of sales volume: rent, insurance, software, salaried payroll, loan payments, internet, and accounting fees. Variable expenses move with your sales volume: inventory, raw materials, packaging, shipping, payment processing, hourly labor, and sales commissions.
This split helps you see which costs you must cover regardless of sales volume and which costs rise as sales increase. It’s also the foundation for the break-even calculation further down, so keep these two lists handy.
Step 4: Calculate Your Cost of Goods Sold (COGS)
COGS looks different depending on your business type—retail, e-commerce, restaurant, manufacturing, or service. For service-based businesses, COGS often includes direct labor or other costs tied directly to delivering the service, rather than lumping everything into general overhead.
Once you know your COGS, the math is simple: Gross Profit = Revenue − COGS. This number tells you what’s actually left to cover everything else, and it’s the figure you’ll carry into your budget example below.
Step 5: Budget for Taxes, Debt, and Irregular Expenses
This is where a lot of basic budgets fall short. Tax treatment varies by business structure and location, so set aside a dedicated tax reserve every month rather than treating it as an afterthought. The IRS Small Business and Self-Employed Tax Center is a solid starting point for understanding what you’ll actually owe and when. Include scheduled debt payments in your cash-flow plan, with principal and interest tracked separately.
For irregular expenses like annual insurance, equipment replacement, licenses, or seasonal inventory, divide the annual cost by 12 and set aside that amount each month in your budget. A $1,200 annual bill means setting aside $100 a month in advance, so it never catches you off guard.
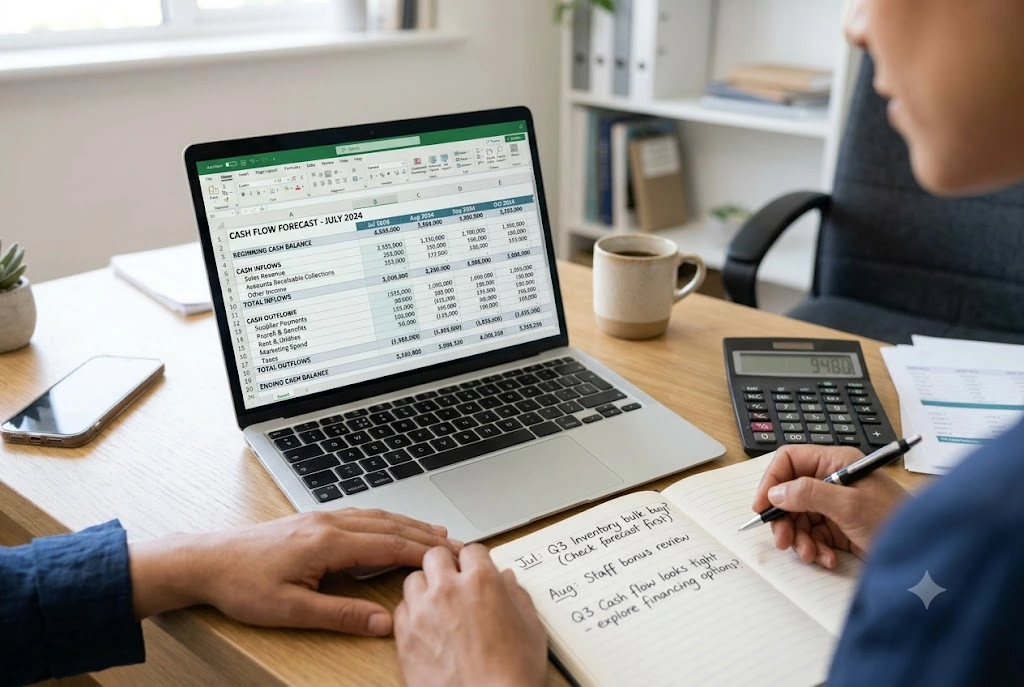
Step 6: Build a Small Business Cash Flow Forecast
A budget and a cash flow forecast solve different problems, which is why this deserves its own section. Track money coming in—cash sales, customer payments, recurring revenue, and any loans or investment—separately from money going out, including operating expenses, payroll, supplier payments, taxes, debt, and owner distributions.
The formula is straightforward: Ending Cash = Beginning Cash + Cash Inflows − Cash Outflows. Running this monthly catches timing problems before they become emergencies—the same discipline that matters most when a business is trying to grow. See How to Scale a Small Business Without Burning Cash for more on that. The SBA’s business guide covers cash flow planning alongside the rest of day-to-day financial management if you want a broader reference.
Step 7: Set Your Spending Priorities
Not every expense deserves equal weight. A simple hierarchy helps you decide fast when money is tight: keep the business running first (rent, payroll, utilities, essential software, suppliers), then protect cash flow (taxes, debt, emergency reserve), then generate revenue (marketing, sales tools, customer acquisition), and finally growth (hiring, equipment, expansion). This turns your budget into a decision-making tool instead of just a spreadsheet—the same prioritization that matters when scaling a small business without increasing operating costs.
How to Calculate Your Small Business Break-Even Point
Once fixed and variable costs are separated, your break-even point tells you exactly how much you need to sell before you start making money. The formula is
Break-Even Units = Fixed Costs ÷ Contribution Margin per Unit
Contribution margin is your price per unit minus the variable cost per unit. So if you sell a service for $100, it costs $40 in variable costs to deliver, and your fixed costs run $6,000 a month, your contribution margin is $60. Divide $6,000 by $60 and you need 100 sales a month just to break even. Each additional sale above the break-even point contributes toward profit, assuming the underlying costs remain consistent.
For businesses that sell multiple products or services, break-even analysis is usually based on an average contribution margin or a contribution-margin ratio rather than a single unit price.
A Simple Small Business Budget Example
Here’s what this looks like for a small service business bringing in $10,000 a month.
| Category | Monthly Budget |
|---|---|
| Revenue | $10,000 |
| COGS / Direct Delivery Costs | $1,500 |
| Gross Profit | $8,500 |
| Administrative / Non-Direct Contractors | $2,500 |
| Rent | $1,000 |
| Marketing | $800 |
| Insurance | $250 |
| Software | $300 |
| Utilities | $200 |
| Other Expenses | $450 |
| Operating Expenses (Subtotal) | $5,500 |
| Tax Reserve | $1,500 |
| Emergency Reserve | $500 |
| Total Budgeted Outflows (COGS + Operating Expenses + Reserves) | $9,000 |
| Budgeted Cash Available | $1,000 |
The contractors listed here are assumed to be administrative or overhead support—not direct service-delivery labor, which would normally be included in COGS as covered in Step 4.
That final $1,000 isn’t automatically profit—it’s what’s left to allocate toward debt paydown, reinvestment, or an owner draw, depending on your priorities and how your business tracks profit for accounting purposes.
Small Business Budget Template
Use this simple structure to track budget versus actual every month.
| Category | Budget | Actual | Difference | Notes |
|---|---|---|---|---|
| Revenue | ||||
| COGS | ||||
| Gross Profit | ||||
| Payroll | ||||
| Marketing | ||||
| Software | ||||
| Rent | ||||
| Taxes | ||||
| Debt | ||||
| Emergency Fund | ||||
| Net Profit |
Net profit and ending cash are not the same—use the cash flow forecast from Step 6 alongside this template to track cash actually available.
How to Make a Budget for a New Small Business
Without historical data, build your first budget around costs you can estimate with reasonable confidence and commitments that are difficult to reverse. Start with supplier quotes, rent, payroll, software, insurance, and other known costs, then model revenue using conservative assumptions. Build three revenue scenarios—conservative, expected, and optimistic—and plan your core spending around the conservative case, not the best-case one. It’s far easier to raise spending later than to cut it after committing to fixed costs too early.
Which Budgeting Method Should a Small Business Use?
There isn’t one universal method—the right one depends on how predictable your revenue and costs are.
Simple Fixed vs. Variable Budget
The approach used throughout this guide. You separate fixed costs from variable ones and plan around a conservative revenue estimate. It’s the easiest to maintain and works well for most small businesses.
Zero-Based Budgeting
Every dollar of expected income is assigned a job—expenses, savings, debt, reinvestment—until nothing is unaccounted for. Each new period starts from zero rather than adjusting the last period’s numbers, which forces you to re-justify every expense. It suits businesses with tight margins or ones actively cutting costs.
Percentage-Based Budgeting
Expenses are planned as a percentage of revenue rather than fixed dollar amounts—useful when revenue swings significantly month to month, since spending scales down automatically in slower periods.
Rolling Budget
Instead of setting a budget once a year, you update it every month or quarter based on the most recent actuals. This suits businesses with fast-changing costs or early-stage companies still learning their real numbers.
For most small businesses, start with a simple monthly fixed/variable budget and add complexity only when it’s actually needed.
How to Track and Adjust Your Budget Every Month
A budget that’s never reviewed isn’t really a budget—it’s a guess you wrote down once. Each month, enter actual revenue and expenses, compare them against your budget, and flag anything with a meaningful gap.
When you spot a variance, categorize it before reacting: was it a one-time expense, something unexpected, recurring overspending, a revenue shortfall, or simply an estimate that was wrong from the start? A one-time expense might need no action at all. Recurring overspending usually means the original category needs to be resized rather than defended every month. This monthly rhythm—enter, compare, categorize, adjust—is what separates a budget that actually works from one that quietly gets ignored.
How Much Should a Small Business Keep in Reserve?
There’s no single percentage that fits every business, and the benchmark should always be expressed against your operating expenses, not your revenue. Financial industry guidance commonly points to three to six months of ordinary operating expenses as a reasonable reserve target, but treat that as a starting point to adjust rather than a fixed rule.
The right number for your business depends on revenue volatility, fixed monthly costs, industry, seasonality, existing debt, payroll size, and access to credit. A business with highly seasonal or unpredictable revenue typically needs a reserve closer to the higher end of that range, while a business with steady, contract-based income can often run leaner.
Common Small Business Budgeting Mistakes to Avoid
- Budgeting from gross revenue without accounting for COGS
- Using optimistic sales numbers instead of conservative ones
- Forgetting annual expenses that only show up once a year
- Ignoring taxes until they’re due
- Mixing personal and business expenses
- Failing to track cash flow separately from profit
- Creating too many expense categories to manage
- Never comparing actual results to the budget
- Treating the budget as fixed instead of a living document
- Forgetting seasonal changes in revenue or costs
Budgeting Tools for Small Businesses
The right tool depends less on preference and more on how complex your business actually is.
| Business Situation | Best Starting Tool |
|---|---|
| Freelancer or solo operator | Simple spreadsheet |
| Small service business | Spreadsheet or entry-level accounting software |
| Ecommerce business | Accounting software with inventory tracking |
| Growing team with payroll | Full accounting software |
| Complex or irregular cash flow | Accounting software plus a dedicated cash-flow forecasting tool |
Start with the simplest tool that covers your situation, and upgrade only when it starts slowing you down rather than saving you time. Once your budget and cash flow tracking are running smoothly, business automation services for small businesses are worth a look for cutting down the manual work.
Small Business Budget FAQs
How do I create a budget for my small business? Start with your last 6–12 months of financial data, estimate revenue conservatively, separate fixed and variable expenses, account for taxes and irregular costs, and then review actual results against your budget every month.
What should a small business budget include? Expected revenue, fixed and variable expenses, COGS, tax reserves, debt payments, an emergency reserve, and a plan for irregular annual costs.
How much should a small business spend on expenses? There’s no universal percentage that applies across industries. Instead, build the number from the ground up: add your fixed operating costs, variable costs, COGS, tax reserve, and target profit margin, then work backward to see what’s actually affordable at your current revenue.
How do I create a small business budget from scratch? Without historical data, use realistic assumptions: expected customer volume, average sale price, supplier quotes, and industry benchmarks, then build conservative, expected, and optimistic scenarios.
What is the best budget method for a small business? Most small businesses do well starting with a simple fixed-vs-variable budget. Zero-based budgeting suits tight-margin businesses, percentage-based budgeting suits businesses with volatile revenue, and rolling budgets suit fast-changing or early-stage companies.
How often should a small business update its budget? Review actual results against your budget every month, and revisit the full budget structure at least once a quarter.
What is the difference between a business budget and a cash flow forecast? A budget outlines planned revenue and expenses over a period. A cash flow forecast tracks the actual timing of money coming in and going out, which can differ from your budget even in a profitable month.
How do I budget when my business income changes every month? Look at your revenue by month across the past 1–2 years to identify your actual seasonal pattern rather than relying on a single low month. Build separate spending expectations for peak and slow periods, and direct surplus cash from strong months into reserves that carry you through the slower ones.
Should taxes be included in a small business budget? Yes—set aside a dedicated monthly tax reserve rather than treating tax payments as a surprise expense.
Do I need accounting software to create a small business budget? No. A spreadsheet is enough to start; accounting software becomes more useful as your transaction volume and payroll complexity grow.
What percentage of revenue should a small business budget for expenses? There’s no universal percentage that works across industries or business models. The right figure depends on your COGS, fixed costs, profit margins, tax obligations, and target profit—a service business with low COGS and a retail business with high COGS will land in very different places even at the same revenue level. Build the number from your actual costs rather than starting with a fixed percentage.
Final Takeaway
A small business budget works when it reflects how your business actually operates—not when it looks perfect in a spreadsheet. Start with historical data, build a realistic revenue estimate, account for every expense including taxes and reserves, know your break-even point, track cash flow separately from profit, and review your numbers every single month.
Start with your last 6–12 months of numbers and build your first working budget today.
Editorial Note: This guide uses publicly available small-business finance guidance, including resources from the U.S. Small Business Administration and the Australian Government. It is intended as general educational information; business-specific tax and financial decisions should be reviewed with a qualified professional.